企业级搬迁服务商
零中断・强保障・成功案例可鉴
20年专注商务搬家,服务超过1000+家企业,见证每一次完美迁移
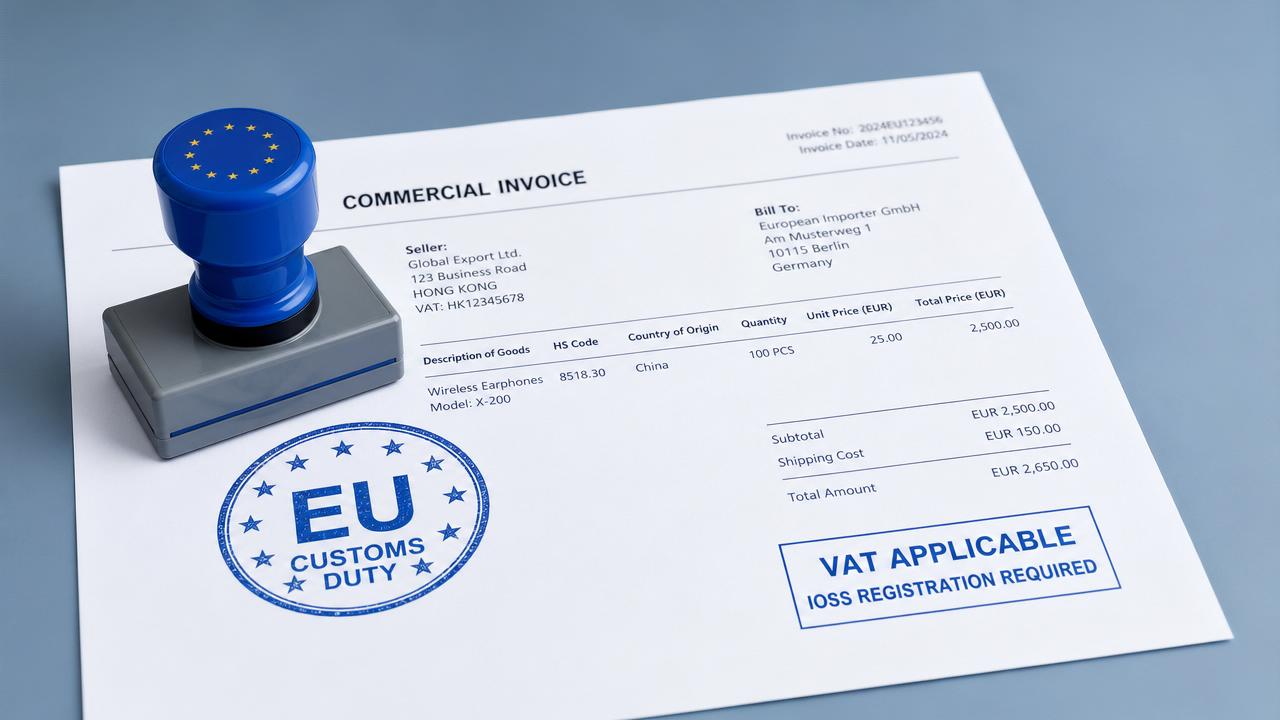
Effective 1 May 2026, the European Union has abolished the Low Value Goods (LVG) exemption, requiring VAT and customs duties on all inbound parcels—regardless of value. This regulatory shift directly affects B2C direct shipping, sample dispatches, and small-batch trial orders, increasing both clearance costs and processing time for small- and medium-sized overseas buyers.
Policy Implementation Effective 1 May 2026
As of 1 May 2026, the EU formally terminated the LVG mechanism. Under the revised rules, every physical parcel imported into the EU—irrespective of declared value—is subject to standard VAT collection and, where applicable, customs duties. The change applies uniformly across all EU Member States and covers all consignment types previously eligible for LVG relief, including e-commerce shipments, commercial samples, and low-volume test orders.
Impact Across Supply Chain Roles
Direct Exporters and E-Commerce Sellers
These entities face immediate operational adjustments: VAT must now be collected at checkout or via IOSS registration, and duty calculation must be integrated into fulfillment workflows. Failure to comply may result in shipment delays or rejection at EU borders.
Procurement and Sourcing Companies
Buyers relying on rapid, low-cost sample verification—especially those evaluating new suppliers or validating product specifications—now encounter longer lead times and higher landed costs per unit. Budgeting and approval cycles for small-value procurement must be revised accordingly.
Manufacturers and Contract Producers
Firms supplying components or finished goods via direct-to-buyer channels must update documentation practices—including commercial invoices, origin declarations, and harmonized system (HS) code accuracy—to support compliant EU entry. Inaccurate classification risks reclassification penalties and retrospective assessments.
Logistics and Customs Service Providers
Third-party logistics operators and customs brokers must enhance digital integration with EU national portals (e.g., EU’s Import Control System 2) and ensure real-time VAT validation capabilities. Manual handling of sub-€150 consignments is no longer viable under the new compliance threshold.
Key Operational Priorities for Businesses
Update VAT Collection and IOSS Registration Strategy
Exporters serving EU consumers must either register for the Import One-Stop Shop (IOSS) or appoint an EU-established intermediary to collect and remit VAT. Non-IOSS shipments will trigger post-import VAT assessment by national tax authorities—adding friction and unpredictability.
Revise Sample and Trial-Order Logistics Protocols
Businesses using small-batch dispatches for quality checks or market testing should reassess cost-per-unit economics and explore consolidated shipping options or regional warehousing to mitigate per-parcel overheads.
Strengthen Documentation Accuracy and Traceability
Commercial invoices must include precise product descriptions, correct HS codes, accurate country-of-origin statements, and validated VAT identification numbers. Discrepancies increase scrutiny risk and may trigger audits or temporary holds.
Adjust Procurement Timelines and Inventory Planning
Extended customs processing windows—particularly for non-pre-cleared consignments—require earlier order placement and buffer stock planning, especially for time-sensitive components or seasonal products.
Industry Perspective: A Shift Toward Structured Compliance
Analysis shows this policy change reflects a broader EU trend toward harmonizing indirect tax enforcement across digital trade channels—not merely raising revenue, but leveling the playing field between domestic and cross-border sellers. From an industry perspective, it effectively raises the compliance entry requirements for non-EU exporters, particularly SMEs lacking dedicated tax operations. What deserves closer attention is how rapidly national customs administrations implement consistent valuation methodologies and whether de minimis thresholds re-emerge in alternative forms (e.g., simplified declaration schemes for certified trusted traders). Observably, the burden is shifting from tariff administration to end-to-end tax process integration.
Strategic Implications for Global Trade Operations
This reform marks a structural recalibration—not a temporary adjustment—in how low-value physical goods enter the EU market. It underscores that agility in international trade now depends less on speed of dispatch and more on precision of tax and customs readiness. For manufacturers and distributors alike, embedding VAT and duty logic into quoting, order management, and logistics execution is no longer optional—it is foundational to market access.
Source Attribution and Monitoring Guidance
This article was generated based solely on the user-provided title, event date (2026-05-01), and summary description. Specific official source links were not provided in the input and should be verified continuously. Stakeholders are advised to monitor updates from the European Commission’s Taxation and Customs Union Directorate-General, national customs authorities, and EU-recognized certification bodies for clarifications on implementation scope, transitional arrangements, and technical guidance on IOSS use cases.
 南京搬办公室需要买搬家保险吗?金融与科技类企业采购决策时如何评估风险覆盖必要性
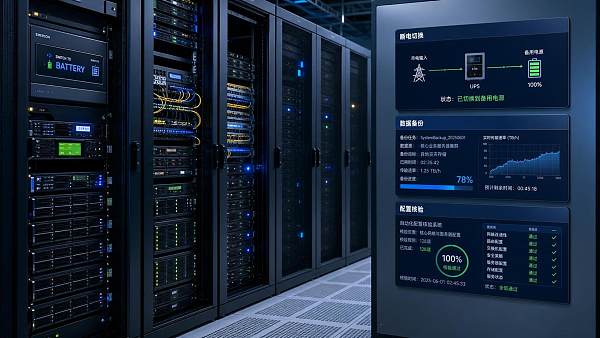
 艺搬搬家南京能不能处理服务器搬迁中的断电风险
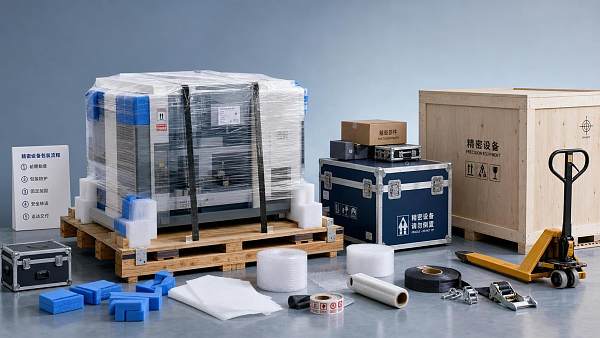
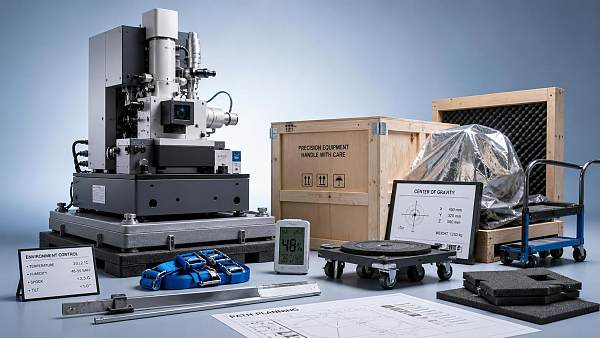
 南京搬家公司设备防护怎么判断是否达到精密仪器要求
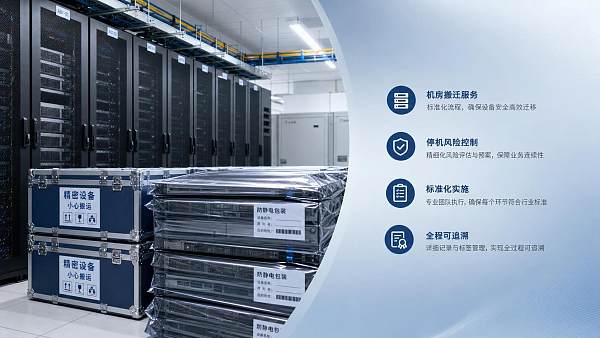
 南京机房搬迁服务怎么选?看懂停机风险与实施能力
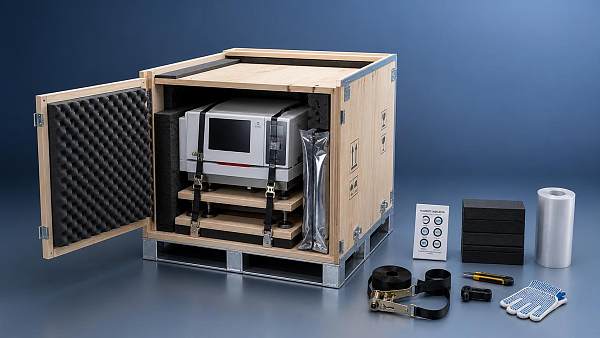
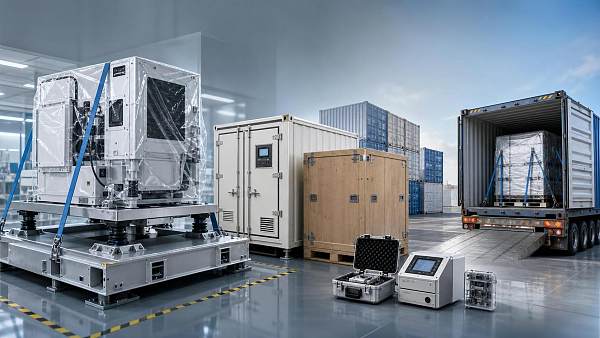
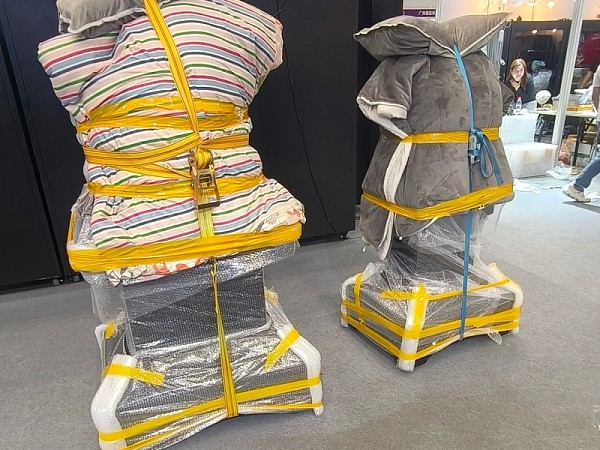
 精密设备搬迁如何避免损坏?关键环节与防护要求解析
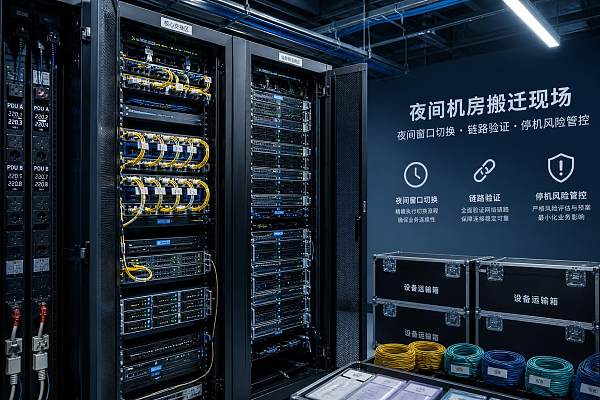
 南京机房搬迁为何多选夜间窗口,停机风险怎么控
 精密仪器搬运看哪些参数,减震方案不是唯一标准
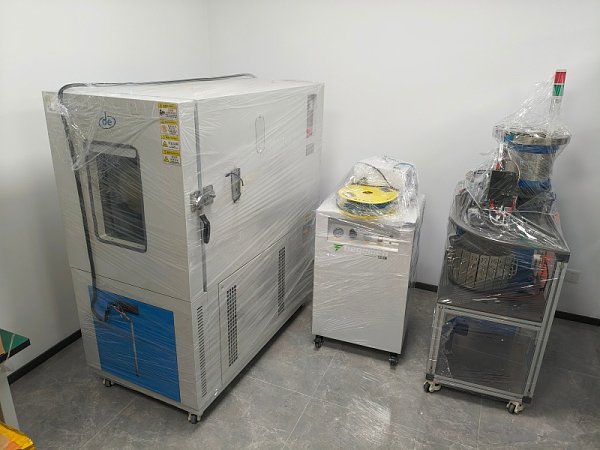
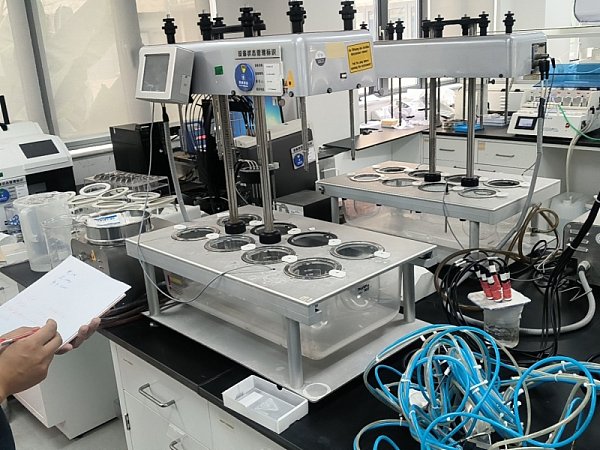
![]() 南京实验室搬迁全流程解析 | 艺搬商务搬家精密设备零误差迁移方案
 南京机房搬家怎么降风险:断电切换与数据备份顺序
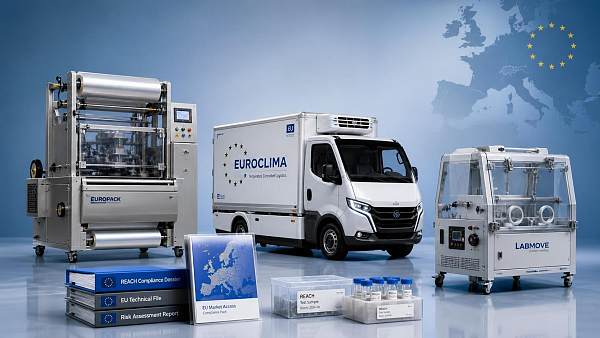
 欧盟REACH新规8月起要求商务搬迁设备申报含物质
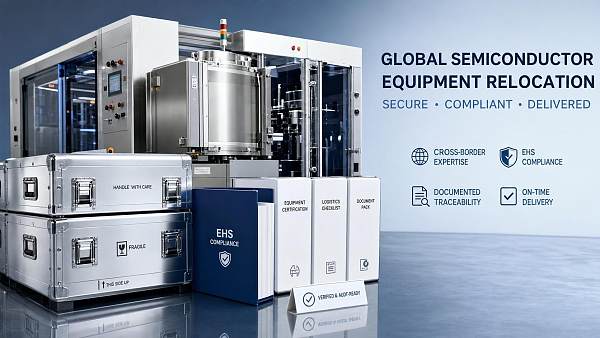
 半导体设备搬迁订单Q2增67%,中国服务商占比升至38%
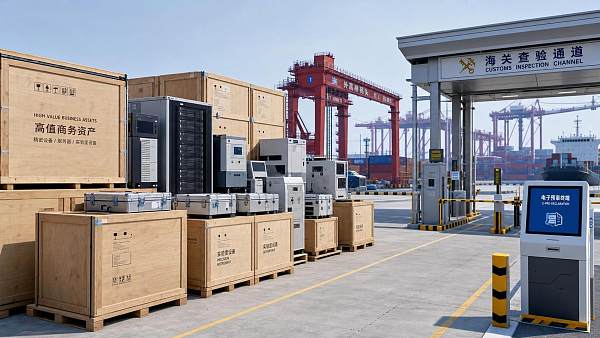
 外高桥港试点高值商务资产绿色通道
 半导体设备搬迁订单增长折射合规服务竞争
 半导体设备搬迁升温,中国服务出口额Q2增67%
 高端制造搬迁升温:Q2中国订单同比增53%,半导体设备占比突出
 Q2中国半导体设备搬迁订单同比增53%
 东南亚办公设备搬迁保险门槛上调
 UL 62841-2-52更新提高IT设备搬迁振动测试阈值
 远东北欧航线调整配载规则,商务设备交付稳定性受关注
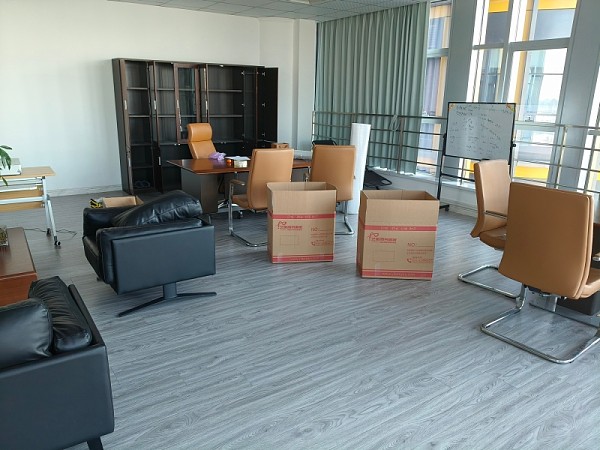
 南京传媒公司办公室搬迁案例_艺搬商务一站式企业搬迁服务
 南京家居公司整体搬迁案例_艺搬商务助力加多多家居零中断乔迁
 南京半导体公司整体搬迁案例_南京芯惠半导体搬迁服务_艺搬商务搬家
 南京传媒公司办公室搬迁案例_南京维仁传媒搬迁全程服务_艺搬商务搬家
 南京珠宝艺术品搬迁案例_龙音珠宝全程无损搬迁_艺搬商务搬家
 南京智能设备公司搬迁案例|佛山市道恩智能设备办公室搬迁服务
 南京律所办公室搬迁案例|律师事务所办公搬迁服务
 南京艺搬商务圆满完成江苏省农垦产业技术研究院实验室搬迁项目
 南京国企办公室搬迁案例|江苏凤凰资产办公搬迁服务
 南京商务搬家案例:锦欣国际物流办公室整体搬迁圆满完成
 南京金融企业搬迁案例_单位搬迁服务_艺搬商务搬家
留言
如果您对我们的产品感兴趣,并想了解更多细节,请在这里留言,我们将尽快回复您。
请给我们留言
联系我们
南京市雨花区花神庙10号
免费热线:400-880-5202
电子邮件:move@njyiban.com
商务合作:biz@njyiban.com
单位搬迁专属报价单
专注写字楼/产业园整体搬迁 · 一站式智能报价